West VirginiaInsurance Appraiser Free file review(844) 537-1427

Independent claim appraisal · 55 counties

West Virginia Insurance Appraiser

Covered, inspected, and still underpaid? As your West Virginia Insurance Appraiser, we build an independent, line-by-line valuation of the damage and take it through the appraisal process written into your policy.

  • Appointed by you, not the carrier
  • Homes, rentals, HOAs & businesses
  • Statewide on-site inspections

Free file review

Two minutes. A call back within one business day.

55counties served, statewide
12appraisal & estimating services
7free in-browser claim tools
2 of 3signatures make an award binding
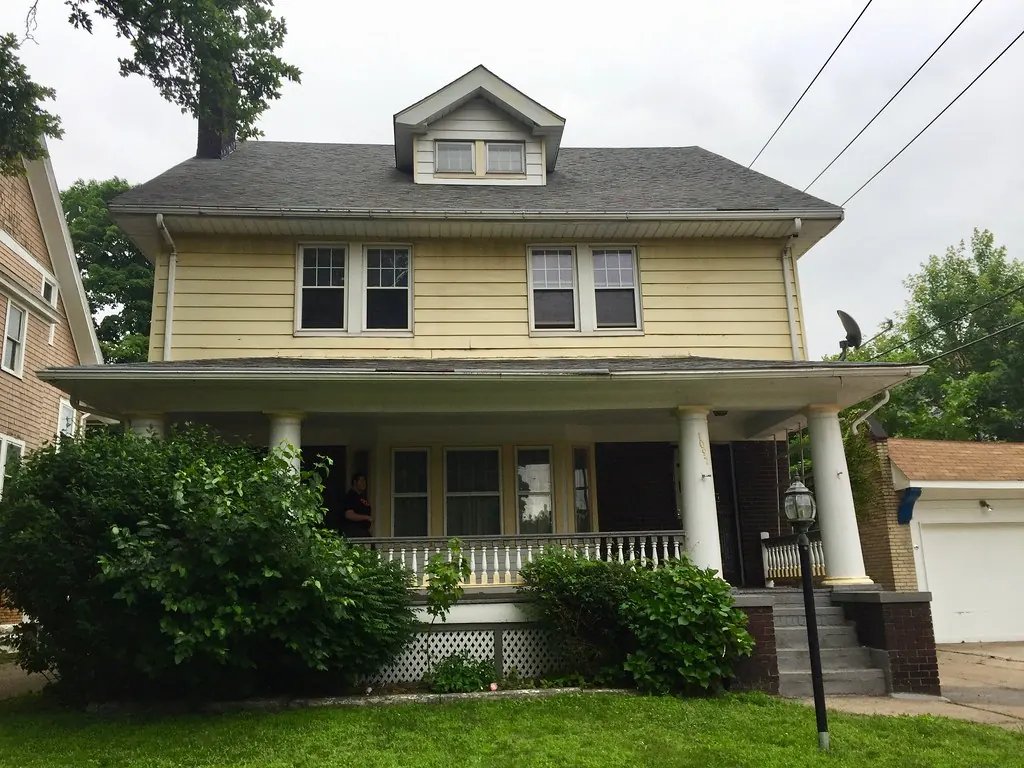
Two-story wood-frame house with a front porch and dormer
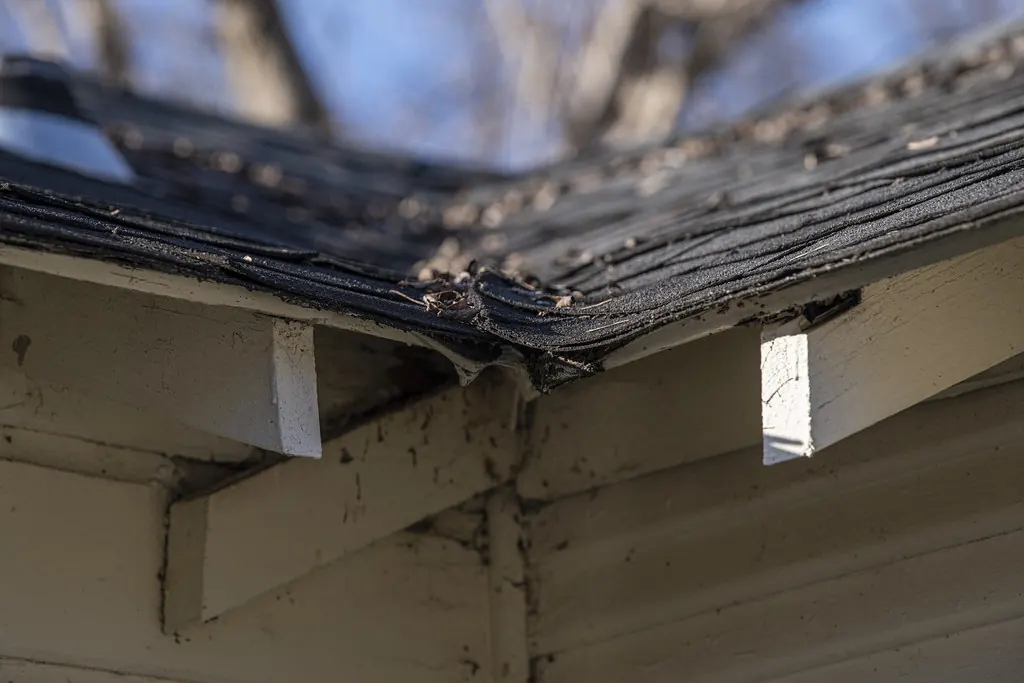
Close-up of damaged asphalt shingles curling at a roof eave

Covered is not the same as paid

When a covered claim still comes up short

Most disputed claims in this state aren’t denials. The adjuster agrees the storm, the frozen pipe or the fire happened — then writes an estimate that leaves out a slope of the roof, prices slate as asphalt, skips the second-story labor or forgets the code upgrade. A West Virginia Insurance Appraiser works in that gap between “covered” and “fully paid.”

We don’t edit the carrier’s estimate. A West Virginia Insurance Appraiser starts over: our own inspection, our own measurements and pricing for your county, so every number we put in front of a panel can be defended.

How the firm works

Twelve services

Where a West Virginia Insurance Appraiser steps in

From a single estimate review to full panel representation and neutral umpire work. Each service has its own page with the West Virginia details that matter.

Appraisal Representation

We act as the appraiser you appoint after an appraisal demand is made under your property policy.View service

Homeowners Claims

Appraisal help for houses, cabins, townhomes and manufactured homes when the carrier’s estimate comes in short.View service

Commercial & HOA Claims

Appraisal support for shops, offices, churches, rental buildings and community associations across the state.View service

Roof & Hail Claims

Help with roof claims on metal, slate and asphalt shingle roofs, including matching and repair-versus-replace disputes.View service

Wind, Derecho & Tornado Claims

Appraisal for straight-line wind, derecho and tornado damage, including the trees that come down with them.View service

Remnant Tropical Storm Claims

Claims from the wind, rain and even snow that the remains of hurricanes bring into the mountains.View service

Water Damage Claims

Appraisal for sudden pipe bursts, appliance leaks and storm-driven water, kept distinct from flood exclusions.View service

Fire & Smoke Claims

Appraisal for structure fires, smoke and soot damage, and wildfire smoke in the southern counties.View service

Mine Subsidence Claims

Help valuing mine subsidence endorsement claims and sorting them from excluded landslide and earth movement.View service

Ice, Snow & Freeze Claims

Appraisal for snow load collapses, ice storm damage, ice dams and frozen or burst pipes.View service

Estimate Review

A line-by-line check of your insurer’s estimate before you decide whether to negotiate or invoke appraisal.View service

Umpire Services

A neutral umpire for West Virginia appraisal panels when the two appraisers cannot resolve every item.View service

Storm history

Floods, derechos and ice: the claims this state remembers

Every big event changes how the next claim is written. A West Virginia Insurance Appraiser prices damage knowing what the last storm did to the same roofs, hollows and river towns.

  1. 1937

    Ohio River flood

    Record January crests swamped river towns from Wheeling to Huntington and led to the floodwalls many cities still rely on.

  2. 1944

    Shinnston tornado

    On June 23 a tornado tore through Shinnston in Harrison County — still the deadliest tornado in state history.

  3. 1985

    Election Day flood

    Early November rains sent the Cheat and South Branch rivers through Parsons, Rowlesburg and the Potomac Highlands.

  4. 2004

    Ivan’s remnants

    In September the leftovers of Hurricane Ivan pushed the Ohio River into Wheeling and other Northern Panhandle towns.

  5. 2012

    The June derecho

    A fast line of storms crossed the state on June 29, toppling trees and leaving much of West Virginia without power for days.

  6. 2012

    Sandy’s mountain snow

    In late October Superstorm Sandy buried Tucker, Randolph and nearby counties in heavy wet snow; roofs and porches gave way.

  7. 2016

    The June 23 flood

    Torrential rain struck Greenbrier, Kanawha and Nicholas counties, devastating White Sulphur Springs, Rainelle, Richwood and Clendenin.

  8. 2021

    Huntington-area ice storm

    In February a thick glaze brought down trees and lines across Cabell, Wayne, Lincoln and Putnam counties.

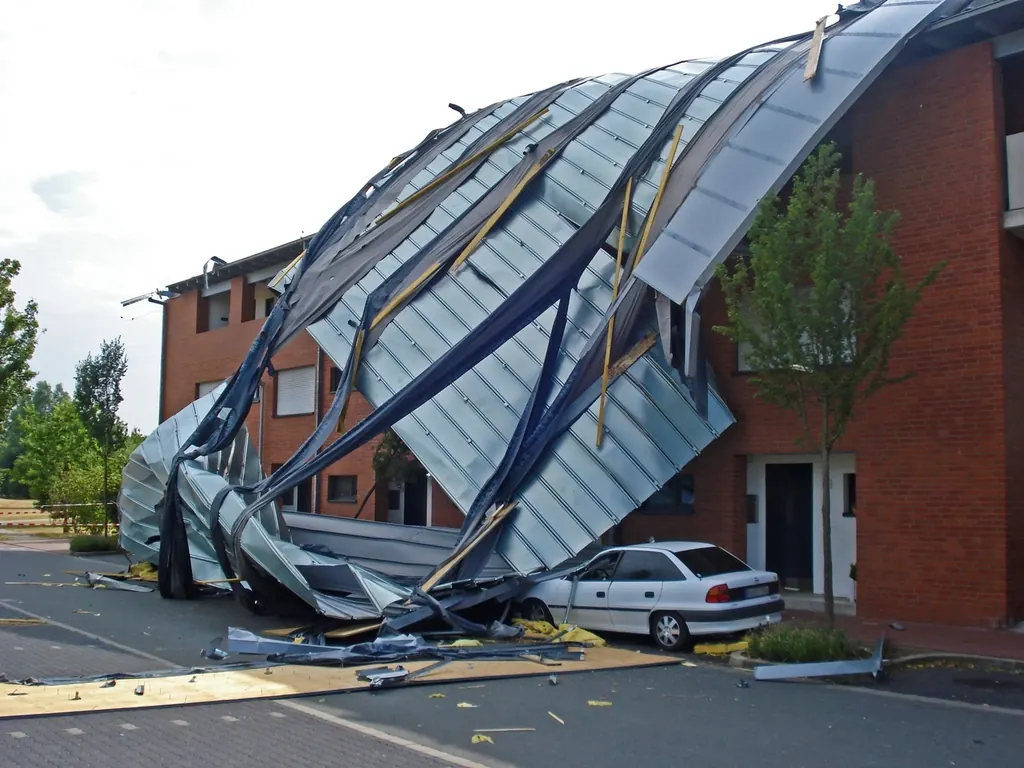
Photos are illustrative and do not show the events described.

How it moves

Five checkpoints between a low estimate and a signed award

The appraisal clause turns an open-ended argument into a defined process. Here is how a West Virginia Insurance Appraiser carries a file from the first call to the award.

  1. 1

    File review

    We read the policy, both estimates and your photos and tell you whether a West Virginia Insurance Appraiser can move the number.

  2. 2

    Independent scope

    Our own inspection, measurements and a line-item estimate priced for your part of the state.

  3. 3

    Written demand

    Appraisal is invoked in writing and your appraiser is named inside the policy’s window.

  4. 4

    Panel work

    Line-by-line negotiation with the insurer’s appraiser narrows the disagreement.

  5. 5

    Signed award

    Anything still open goes to a neutral umpire; two signatures set the amount of loss.

Read the full seven-stage guide

Try it now

Put your two estimates side by side

Type in the insurer’s total and your contractor’s total. A large gap is worth a conversation with a West Virginia Insurance Appraiser; a small one may close faster with a documented supplement.

The full claim gap & fee estimator adds appraiser and umpire fees and shows cautious, likely and strong outcomes.

Side-by-side gap checkNo sign-up
50%
of the disputed amount
Amount in dispute$0
Gap vs. carrier estimate—
Projected award$0
Increase before fees$0

Seven regions

From the Northern Panhandle to the coalfields

The same policy reads differently on a Wheeling rowhouse, a Martinsburg subdivision and a cabin above Canaan Valley. A West Virginia Insurance Appraiser has to know how each region’s weather and housing show up in an estimate.

Wheeling · Weirton · Moundsville

Northern Panhandle

  • River flooding
  • Thunderstorm wind
  • Hillside slips
  • Fire in older buildings

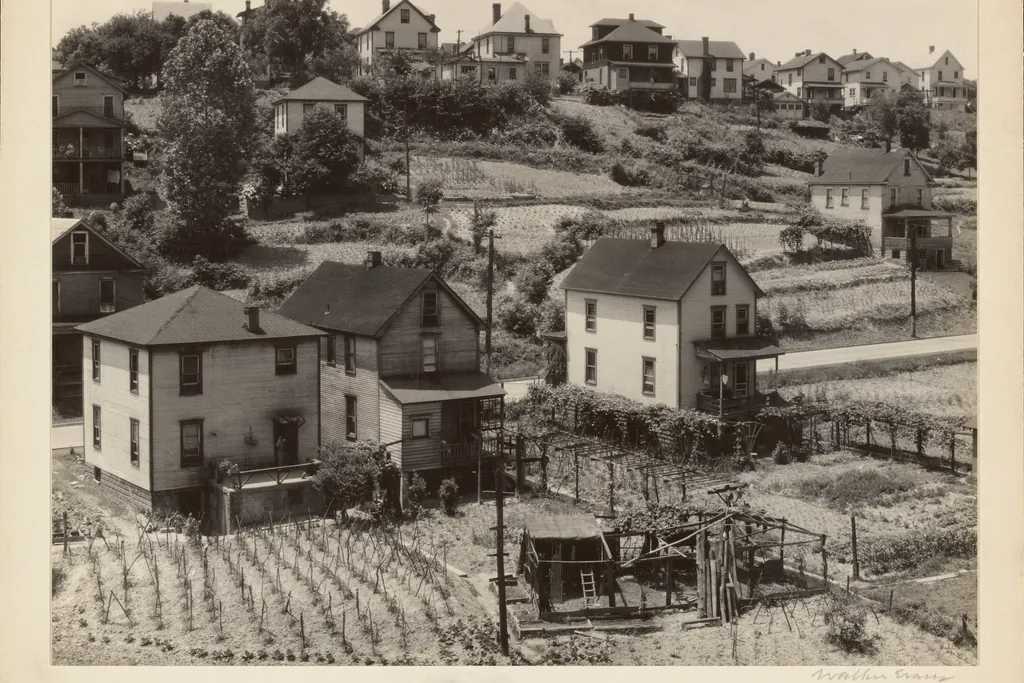
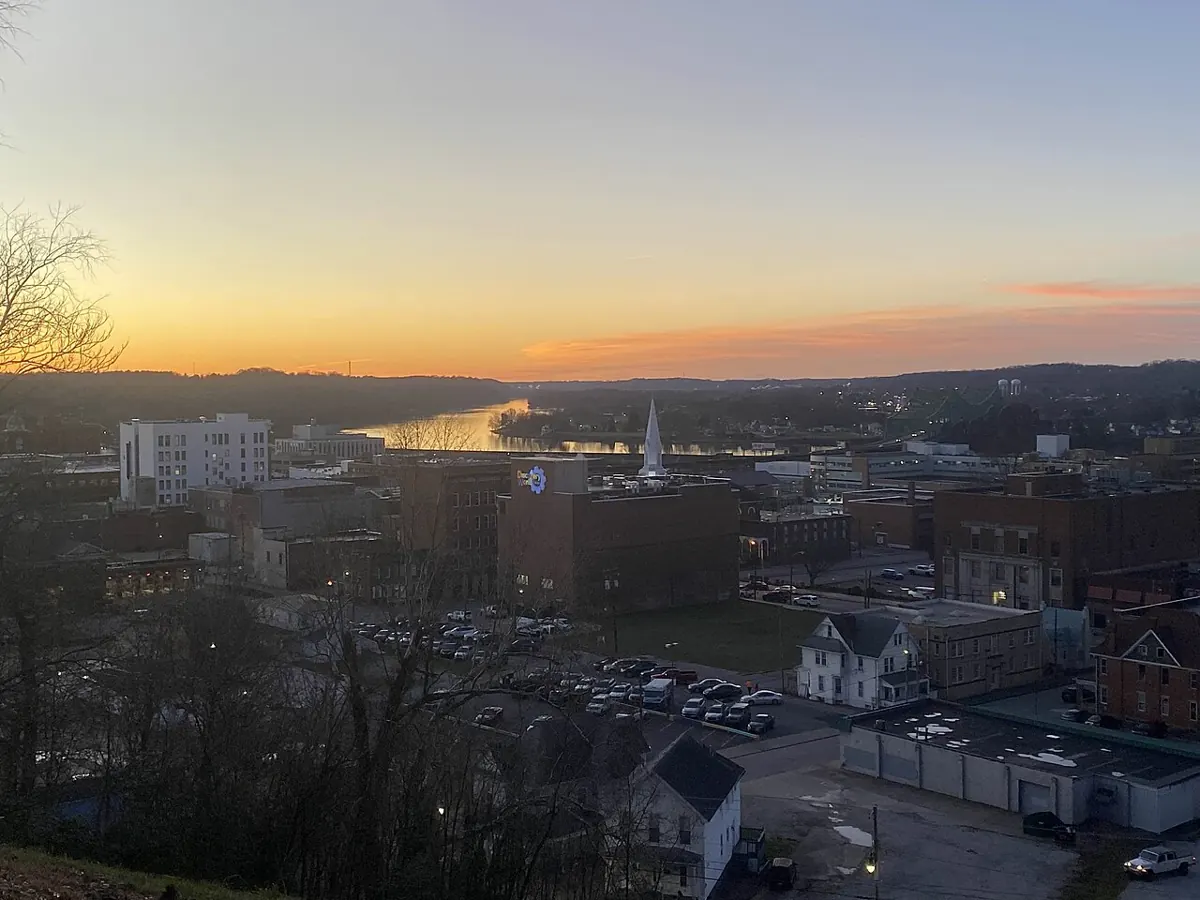
Claims here often involve brick rowhouses, shared walls and historic masonry that standard estimates price poorly. River and creek flooding is a constant backdrop, so separating covered storm water from excluded flood is a frequent fight.
Martinsburg · Charles Town · Shepherdstown

Eastern Panhandle

  • Hail
  • Derechos
  • Heavy snow
  • Ice storms

Fast-growing subdivisions bring siding and shingle matching disputes that older parts of the state see less often. At the same time, 1700s and 1800s stone and brick buildings need specialty repairs that generic line items miss.

Morgantown · Fairmont · Clarksburg

North-Central (Mon Valley / I-79)

  • Mine subsidence
  • Thunderstorm wind
  • Landslides
  • Heavy snow

Old mine workings under many neighborhoods make foundation claims a regular question of subsidence versus settlement versus landslide. Steep lots and dense rental housing near the universities add access and loss-of-rent issues.

Parkersburg · Vienna · Williamstown

Mid-Ohio Valley

  • River flooding
  • Hail
  • Ice storms
  • Thunderstorm wind

Victorian homes and river-town construction mean many losses involve historic materials and craftsmanship. Water claims often turn on whether damage came from river flooding or from a storm opening in the roof.

Charleston · Huntington · South Charleston

Metro Valley (Charleston–Huntington)

  • Flash flooding
  • Ice storms
  • Falling trees
  • Landslides

Homes split between creek bottoms and steep hillsides, so a single storm can bring wind, runoff and slope damage that carriers try to separate. Older housing in the East End and around Ritter Park raises plaster, slate and code-upgrade disputes.

Beckley · Bluefield · Logan

Southern Coalfields

  • Ice storms
  • Mine subsidence
  • Flash flooding
  • Wildfire

Coal-camp houses, manufactured homes and older frame construction make scope and pricing disputes common. Mine subsidence questions and narrow, steep access roads also raise costs that estimates frequently overlook.

Elkins · Lewisburg · Petersburg

Potomac Highlands & Greenbrier Valley

  • Heavy snow
  • Flash flooding
  • Frozen pipes
  • Sinkholes

Snow-load collapses, vacant cabin pipe bursts and remote access costs drive many claims in the mountains. Karst terrain and the memory of the 1985 and 2016 floods make coverage questions about ground movement and water especially sharp.

Cities we visit most

On-site in all 55 counties

We inspect in person statewide. These twelve local pages cover the places a West Virginia Insurance Appraiser is called most often, with neighborhoods, housing and storm history for each.

See every service area

Know the limits

What appraisal can and can’t decide

A good West Virginia Insurance Appraiser tells you early when a different kind of help fits better.

Appraisal can settle

  • How much a covered loss costs to repair
  • Repair-versus-replace and matching disputes
  • Missing trades, steep and high charges, code items
  • Overhead and profit when the policy allows it
  • Replacement cost and actual cash value figures

Appraisal can’t settle

  • Whether a loss is covered or excluded (flood, landslide)
  • Bad-faith or unfair-practice claims
  • Late-notice or misrepresentation defenses
  • Deadlines that already need an attorney
  • Disputes too small to justify fees

Questions

Straight answers before you sign anything

Common questions property owners ask a West Virginia Insurance Appraiser about cost, timing and when appraisal is the wrong move.

What does a West Virginia Insurance Appraiser do that my adjuster doesn’t?

Your adjuster works for the insurer and writes the company’s estimate. A West Virginia Insurance Appraiser is appointed by you under the policy’s appraisal clause to build an independent valuation, work through the differences with the insurer’s appraiser and, if needed, present the open items to an umpire.

Is appraisal the same as suing the insurance company?

No. Appraisal is a process written into most property policies to settle disagreements over the amount of loss. It does not decide coverage or bad-faith questions, which are matters for a West Virginia attorney.

When is it worth calling a West Virginia Insurance Appraiser?

When the insurer has accepted coverage, you have its itemized estimate, and the difference from your contractor’s estimate is meaningful — often more than about 10% or several thousand dollars.

Is the appraisal award binding?

On the amount of loss, generally yes, once two of the three panel members sign. That is why the scope should be complete before appraisal is demanded.

How are appraisal fees handled?

Each side usually pays its own appraiser and half of the umpire. We put our fee in writing before any work starts, and the first conversation is free.

Can appraisal help with mine subsidence or landslide damage?

If the insurer agrees a subsidence loss is covered but disputes the cost, appraisal can value it within the endorsement’s limit. If the dispute is whether the ground movement is covered at all, that is a coverage question rather than an appraisal question.

Before you cash the last check

Ask a West Virginia Insurance Appraiser to compare the line items first

A short review now can keep you from accepting a settlement that won’t cover the repair.

Start here

Start with a free file review

Tell us what happened and what the insurer offered. We’ll look it over and give you a straight answer about whether appraisal is worth pursuing.

Tell us about the claim

Free review, no obligation. We usually reply within one business day.

CallFree review